Divorce involves much more than dividing assets and determining who pays which bills. Your financial life is changing, and your credit can be affected along the way.
Joint credit cards, mortgages, auto loans, personal loans, and other shared financial obligations can create challenges during a divorce. Even if a divorce agreement assigns a debt to one spouse, it may not automatically remove the other spouse’s responsibility to the creditor.
That is why protecting your credit should be part of your financial planning from the beginning of the divorce process, not something you address after the divorce is final.
At Divorce Resolutions of New England, we help clients understand the financial implications of divorce and make informed decisions about their financial future. Here are nine steps to consider when protecting your credit during divorce.
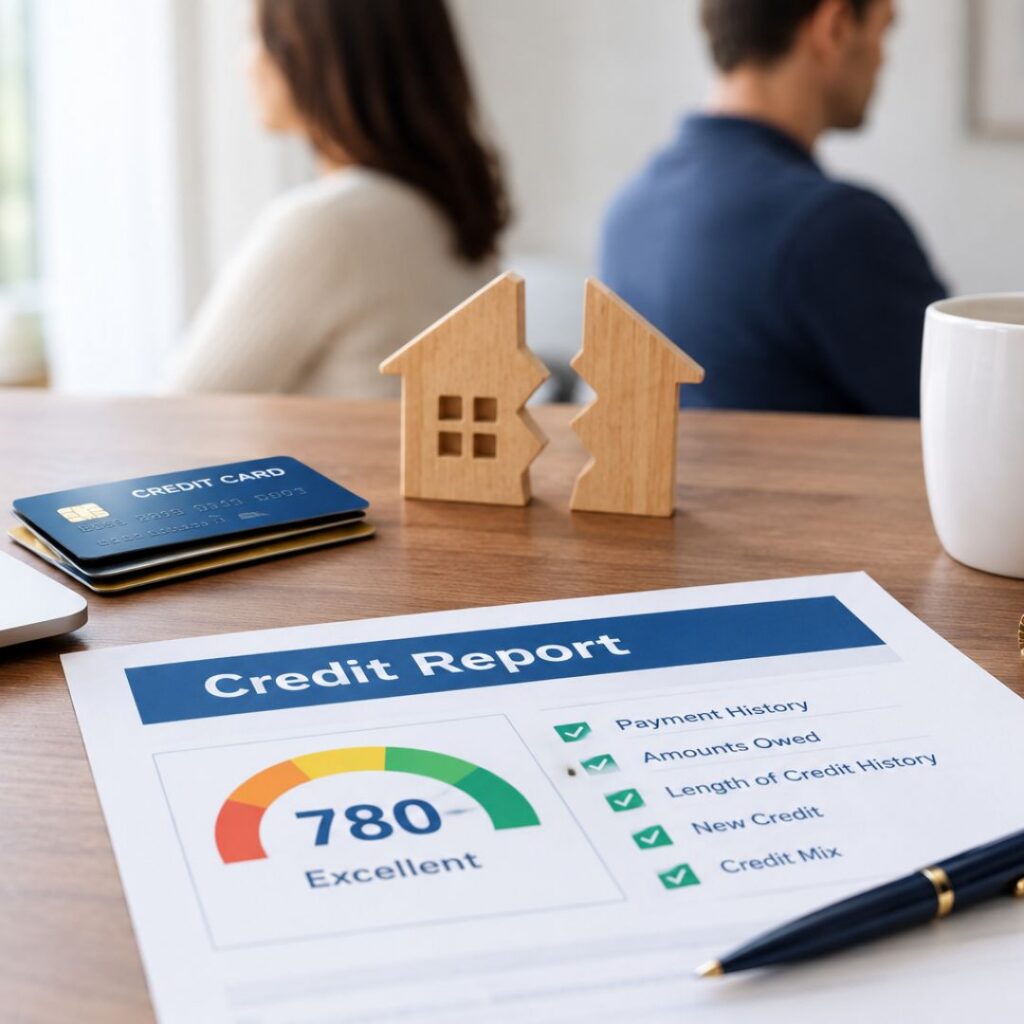
1. Pull All Three of Your Credit Reports
Before you can protect your credit, you need to understand what is currently reporting in your name.
Obtain your credit reports from Equifax, Experian, and TransUnion and review them carefully.
Make a list of:
- Joint credit cards
- Individual credit cards
- Mortgages and home equity loans
- Auto loans
- Personal loans and lines of credit
- Accounts where you are an authorized user
- Past-due accounts or collections
- Any accounts or inquiries you don’t recognize
This is an important first step because you may discover accounts or balances you were not aware of—or obligations that need to be addressed as part of the divorce.
2. Identify Every Joint Debt
One of the most common credit misconceptions during divorce is assuming that the divorce agreement automatically changes your responsibility to a lender.
It doesn’t necessarily work that way.
For example, your divorce agreement might state that your spouse is responsible for paying a joint credit card. However, if your name remains on the account, the creditor may still consider you responsible for the debt.
This distinction between legal responsibility between spouses and contractual responsibility to a creditor is extremely important.
Make a complete list of joint debts and discuss how each should be handled as part of your overall divorce financial plan.
3. Protect Your Individual Accounts
Take inventory of the accounts that are solely in your name and make sure you can access and monitor them.
Depending on your circumstances, this may include changing passwords, updating account contact information, enabling account alerts, and reviewing recent transactions.
If you are concerned about unauthorized activity or access to an account, contact the financial institution directly to understand what steps are available.
The goal is to maintain control over your individual financial accounts while the divorce is underway.
4. Monitor Your Credit Throughout the Divorce
Your credit report should not be a “check it once and forget about it” item.
Financial circumstances can change quickly during a divorce. A joint account balance can increase, a payment can be missed, or an account can be closed.
Regularly monitoring your credit can help you identify issues early.
Pay particular attention to:
- New accounts or inquiries
- Changes in account balances
- Missed or late payments
- Changes to credit limits
- Accounts being closed
- Collection activity
- Information that appears inaccurate or unfamiliar
The sooner you identify a problem, the sooner you can determine what needs to be done.
5. Don’t Let a Dispute Turn into a Missed Payment
Divorce negotiations can become complicated, particularly when spouses disagree about who should pay a particular expense.
But creditors generally aren’t parties to your divorce negotiations.
If you are jointly responsible for an account, a missed payment can potentially affect your credit even if you believe your spouse was supposed to make the payment.
This is one reason it is important to understand your ongoing obligations while the divorce is pending and have a clear system for making sure bills are paid on time.
If there is a dispute over who should pay a debt, discuss the situation with your divorce attorney and financial professional rather than simply allowing the payment to go unpaid.
6. Think Carefully Before Closing Joint Credit Accounts
It can be tempting to immediately close every account you share with your spouse.
However, closing an account doesn’t necessarily eliminate the balance or release either borrower from responsibility. Depending on the circumstances, closing accounts can also affect your available credit and credit profile.
Before closing, transferring, or refinancing an account, determine:
- What happens to the existing balance?
- Who remains legally responsible for the debt?
- Can the account be refinanced or transferred?
- Will the lender release one spouse from liability?
- What impact could closing the account have on your individual finances?
The right solution may differ from account to account.
7. Begin Establishing Your Own Credit Profile
For some people, divorce is the first time they have had to manage credit independently.
If most of your credit history has been tied to your spouse, take the time to understand your individual credit profile and identify any gaps.
Establishing individual credit doesn’t mean taking on unnecessary debt. It means making sure you have a financial foundation that is independent of your former spouse.
Your post-divorce financial plan should consider how your individual credit will support your future needs, including housing, transportation, insurance, and other major expenses.
8. Build a Realistic Post-Divorce Budget
Your credit and your budget are closely connected.
When one household becomes two, expenses can change dramatically. Housing costs, insurance, utilities, transportation, childcare, and debt payments may all need to be reconsidered.
Before making financial decisions during or after divorce, develop a realistic picture of what your cash flow will look like as a single household.
Ask yourself:
- What will my income be?
- What will my fixed expenses be?
- Which debts will I be responsible for?
- What can I realistically afford each month?
- How much emergency savings will I need?
Understanding these numbers can help you avoid relying on credit to fill a budget gap after the divorce.
9. Get Professional Financial Guidance
Divorce creates financial decisions that can have consequences well beyond the divorce itself.
Questions about debt, credit, mortgages, retirement accounts, taxes, investments, cash flow, and dividing marital assets often need to be considered together, not in isolation.
A divorce financial professional can help you understand the financial implications of different settlement options and develop a plan for your post-divorce life. Your attorney can advise you regarding the legal aspects of your divorce and your obligations.
At Divorce Resolutions of New England, we help clients understand the financial side of divorce so they can make informed decisions about their financial future.
Your Credit Is Part of Your Financial Future
Divorce is a major financial transition. Protecting your credit during the process can help give you greater flexibility as you move into your next chapter.
Start by understanding your credit reports, identifying joint obligations, monitoring your accounts, making payments on time, and creating a realistic post-divorce financial plan.
Most importantly, don’t wait until the divorce is finalized to begin thinking about your financial future.
The financial decisions made during divorce can affect your life for years to come. Understanding the numbers clearly can help you move forward with greater confidence and clarity. Contact us for a consultation.